Your Claim Was Denied.
That Doesn't Mean They Were Right
Licensed. Regulated. Accountable.
Mirza Law is a regulated law practice. Our attorneys are licensed by the Law Society of Ontario and carry mandatory professional liability insurance.
Do I have a case?
Take a moment to see if you're eligible
Your partner on the path toYour partner tobeing heard.
Whether your long-term disability claim was denied, cut off, or stuck in appeal, Mirza Law is here to recover what you're owed so you can move on.
Your denial letter, annotated.
Dear Claimant,
"We have determined that you do not meet the definition of total disability under your policy"
That is a conclusion, not a diagnosis. Total disability is a contractual test with specific words in your policy, and the medical evidence is what decides it.
"The medical documentation on file does not support restrictions of a severity that would preclude work"
The most common reason given, and the most answerable. Chronic pain, depression and fibromyalgia are real and disabling, and none of them shows up on a scan.
"Our independent medical consultant has reviewed your file"
Arranged and paid for by the insurer, who chose the doctor. A file review by someone who never met you does not override years of treatment records.
"You may appeal this decision in writing within 60 days"
Their deadline, not the law's. Their internal appeal is their own process, it is optional, and it does not reliably stop the two-year clock that actually matters.
Sincerely,
Claims Department
From denial
to benefits restored
Free review
Send your denial letter, your policy and your medical file. We read the wording that actually governs your claim and find where their reasoning breaks.
The case they can't wave away
We build the medical evidence properly and put a complete legal argument to the insurer, answering every reason they gave. Most claims resolve here, with no courtroom.
Resolution
Back benefits, benefits going forward, interest, and where it applies, damages for the way they handled it. This chapter closes and you move forward.
Your claim isn't just the monthly cheque.
A denied claim is more than the payments you have missed. Back benefits from the date they stopped, benefits going forward or a lump sum in place of them, and interest on all of it.
Where the way they handled the claim caused real harm, that becomes its own claim on top. The free review prices every line.
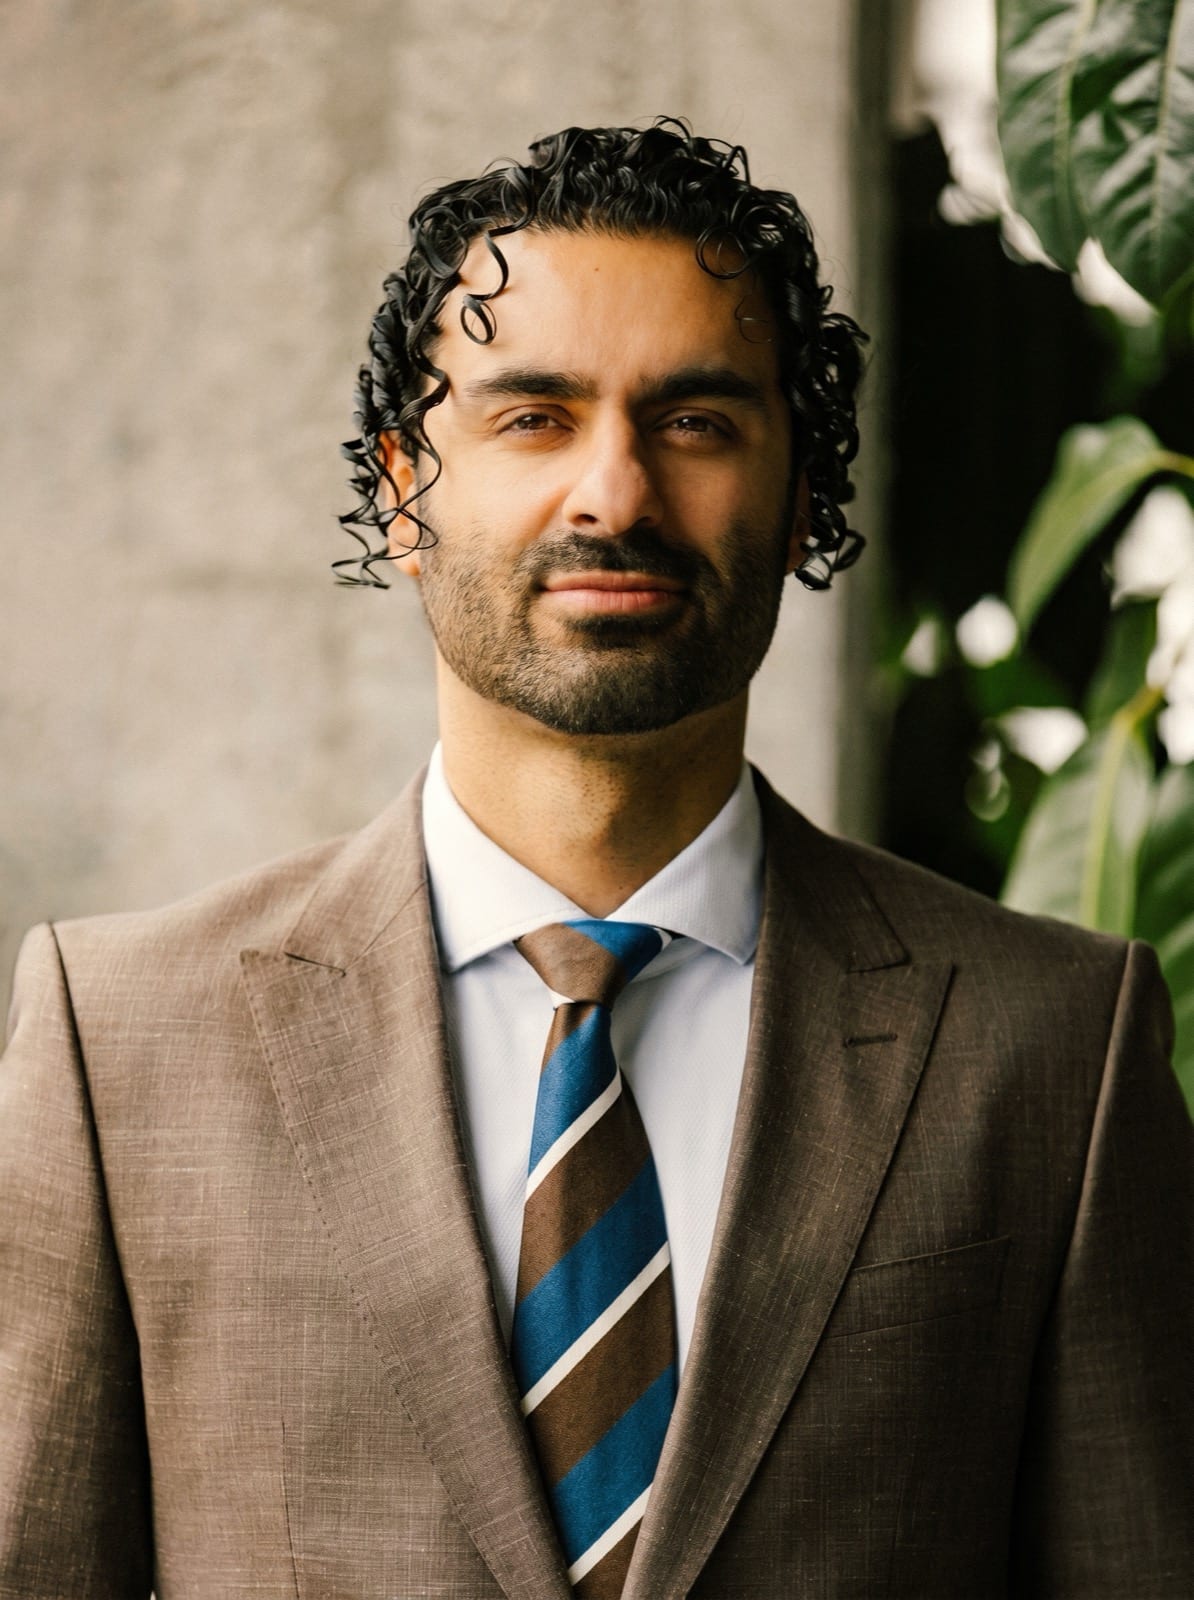
Amir Mirza
Managing Attorney
Licensed: 2017Long-term disability claims in Ontario, explained
A denial isn't a medical verdict
Insurers deny a lot of valid claims, because most people give up after the first letter. The doctor whose name is on your denial usually never met you and read your file for an hour. A denial is a business decision, not the final word on whether you're disabled.
The deadline that actually matters
There's a two-year window to take legal action, and it starts from the date of the written denial. Internal appeals don't pause it. A lot of people spend that window appealing to the same insurer that denied them, and only realize too late that the real deadline was running the whole time.
Mental health claims count the same as physical ones
Depression, anxiety, PTSD, burnout, post-concussion symptoms, all of these qualify when a doctor confirms you can't work. You don't need a psychiatrist or a perfect diagnosis to start; a family doctor's note is enough. The law is clear that mental health claims have to be treated the same as physical ones.
What changes at the two-year mark
After two years on LTD, the test in most policies shifts from whether you can do your own job to whether you can do any occupation suited to your training and experience. Insurers often imply that means any job at all. It doesn't. It has to be real work that matches your background and pays close to what your benefits pay. If no such job exists for you, you're still entitled.
IMEs and surveillance, in perspective
Two things that worry people more than they should:
The rule that protects you is consistency: what you tell your doctor, what you tell the adjuster, and what's visible online should all line up.
Why a call changes the dynamic
Once a lawyer is on file, the insurer stops contacting you directly, which is a relief most people don't expect. We work on contingency, so there's no cost to ask, and a short conversation can tell you whether your claim is worth pursuing and what the timeline really looks like.
Our Clients
Mirza Law has earned 4.8 stars on Google, and
is also top-rated by Best Lawyers Canada, TrustAnalytica, and others
I couldn't be happier with the legal representation I received from Mirza Law. Amir negotiated a significantly higher severance package from what I was initially offered. I’m very grateful for the outcome. He explained every step of the process and was responsive throughout my case.
I highly recommend Amir Mirza if your long-term disability insurance claim was denied and you are considering taking legal action. Amir provided me with several options and explained how the process works very thoroughly. He took the time to answer all of my questions and concerns and always responded in a timely manner. I appreciated his caring approach during a stressful time in my life and never felt pressured to pursue litigation when speaking with him.
Mirza Law was professional, responsive, and easy to work with. The team provided clear guidance throughout the process and made everything straightforward to understand. I appreciated their support and would recommend them to anyone looking for reliable legal assistance.
I can't say enough great things about my experience with this firm. Amir was incredibly helpful and secured a much better settlement than I was initially offered. Couldn't have asked for more. I would definitely recommend Mirza Law.
My wife's long term disability benefits were cut off after two years and the team at Mirza Law helped us to get them back. We were working with Amir who dealt with our insurance company directly. He took the time to explain the whole process and laid out our options so we always understood where things stood.
I reached out to this law firm after being denied by Manulife for my long term disability benefits. Amir is genuinely one of the kindest and caring lawyers I have ever met. He guided me through this very difficult period in my life. I understood each part of the process and never felt rushed.
I couldn't be happier with the legal representation I received from Mirza Law. Amir negotiated a significantly higher severance package from what I was initially offered. I’m very grateful for the outcome. He explained every step of the process and was responsive throughout my case.
I highly recommend Amir Mirza if your long-term disability insurance claim was denied and you are considering taking legal action. Amir provided me with several options and explained how the process works very thoroughly. He took the time to answer all of my questions and concerns and always responded in a timely manner. I appreciated his caring approach during a stressful time in my life and never felt pressured to pursue litigation when speaking with him.
Mirza Law was professional, responsive, and easy to work with. The team provided clear guidance throughout the process and made everything straightforward to understand. I appreciated their support and would recommend them to anyone looking for reliable legal assistance.
I can't say enough great things about my experience with this firm. Amir was incredibly helpful and secured a much better settlement than I was initially offered. Couldn't have asked for more. I would definitely recommend Mirza Law.
My wife's long term disability benefits were cut off after two years and the team at Mirza Law helped us to get them back. We were working with Amir who dealt with our insurance company directly. He took the time to explain the whole process and laid out our options so we always understood where things stood.
I reached out to this law firm after being denied by Manulife for my long term disability benefits. Amir is genuinely one of the kindest and caring lawyers I have ever met. He guided me through this very difficult period in my life. I understood each part of the process and never felt rushed.

Common questions
about a denied claim
Every situation, covered
Get your denied claim reviewed.
Get your denied claim reviewed.
Guides on long-term disability
- Your LTD Claim Was Denied in Ontario. What Now? →
- LTD "Own Occupation" vs "Any Occupation": The 2-Year Change →
- Suing Your Disability Insurer for Bad Faith in Ontario →
- How to Apply for Long-Term Disability in Ontario →
- Can a Severance Release Wipe Out Your LTD Claim? Ontario Courts Say Not Always →
- The Independent Medical Exam (IME) in a Disability Claim →